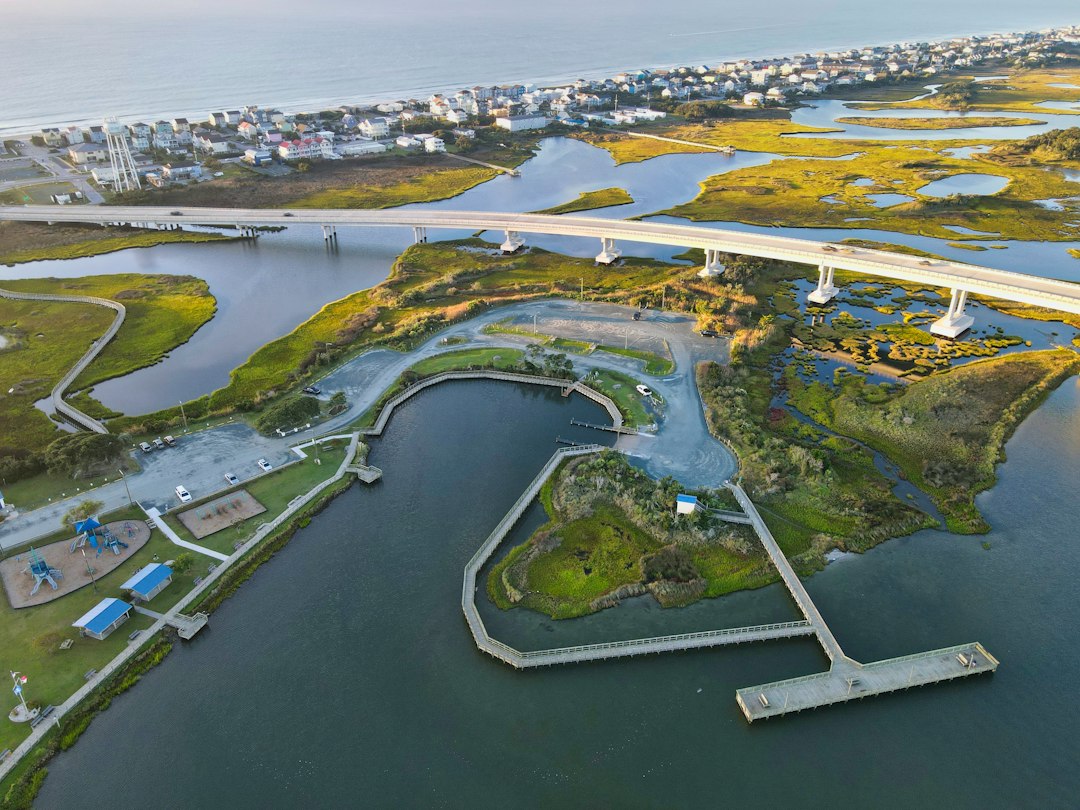
Every beach house on Hatteras Island is essentially a bet on N.C. 12 staying open. I don’t mean that as a scare tactic — I mean it the same way I’d mean it about a harbor entrance with a shifting bar: the access channel is the whole thing. Without it, you don’t have an investment. You have a structure on sand.
I’ve watched buyers fall hard for a cottage in Rodanthe or a canal house in Avon, then look blank when I ask them what their plan is for overwash events. Most of them have never thought about it. They’ve driven down on a clear October Saturday, the road is dry and empty, and the idea that it could be under two feet of Atlantic seawater by February doesn’t register. It needs to register.
What Overwash Actually Does to the Road — and to Access
N.C. 12 runs the entire length of Hatteras Island and continues through Pea Island National Wildlife Refuge before hitting Oregon Inlet. That Pea Island segment is the pinch point. There’s no alternate route. The refuge blocks any bypass, and the terrain — a strip of sand rarely wider than half a mile — leaves almost no room to maneuver. When a nor’easter pushes water over the road there, everyone south of the washover is cut off until NCDOT can pump and reopen.
Closures can run from a few hours to several days. After significant storms, I’ve seen Hatteras cut off for the better part of a week. NCDOT has been working on faster pumping response — Dare County pushed hard on that after a July flooding event that caught a lot of people off guard — but faster doesn’t mean instant, and it doesn’t mean the road won’t close again two weeks later when the next system rolls through.
The Buxton-to-Hatteras Village stretch has its own exposure, though the dune line there is marginally better than north of Salvo. Still, anyone buying south of the Oregon Inlet bridge should look at NCDOT closure history, not just storm history, before they sign anything.
How This Affects Property Values — Honestly
Here’s what I’ve seen in practice. Properties in Avon and Buxton — south of the worst overwash sections but accessible via the main road — tend to hold value reasonably well, partly because they benefit from nourishment work around Buxton and partly because buyers accept the risk as a known quantity. The Buxton beach nourishment project has done real work stabilizing the shoreline there, and that matters for long-term access as much as for the beach itself.
Properties closer to Rodanthe and Waves, north of the most vulnerable sections, see more volatility. When N.C. 12 floods repeatedly in a season, short-term rental revenues drop — sometimes sharply — because guests can’t get in or are stranded and want refunds. Rental operators I’ve talked to at the Hatteras marinas say a bad overwash winter can knock 10 to 15 percent off their annual gross. That kind of income uncertainty shows up in appraisals and in buyer negotiations.
For raw valuation numbers: Hatteras Island residential properties were trading last I checked in a wide band from the mid-$300Ks for smaller interior lots up past $1M for oceanfront or canal-front with good rental history. Don’t take those figures as fixed — the market there moves with storm seasons, insurance markets, and the ongoing drama around N.C. 12. Worth confirming current comps with someone who pulled data in the last 90 days.
Insurance and What the Closure Risk Triggers
Road closure risk isn’t a direct line item on your insurance policy, but it connects to several things that are.
Flood insurance through the NFIP is required for most federally backed mortgages in Dare County’s higher-risk zones, and Hatteras Island is heavily mapped into those. Deductibles on NFIP policies for residential structures have been running in the $1,000 to $10,000 range depending on coverage level and building type, as of my last review — but worth confirming because NFIP pricing has been adjusting under Risk Rating 2.0. North Carolina private flood market options exist and in some cases offer broader coverage, but premium quotes vary substantially by elevation and proximity to the shore.
Wind coverage is separate and tends to be expensive here. I wouldn’t close on anything in Dare County without getting a current insurance quote first, not after. I’ve seen buyers get a nasty surprise at the finish line because they budgeted for last year’s rates.
Rental income insurance — sometimes called business interruption for short-term rentals — is worth asking about specifically. If your property is inaccessible for eight days because N.C. 12 is underwater, that’s eight days of lost bookings. Some policies will cover that. Many won’t, unless you read the fine print carefully and ask the right questions up front.
What the Long-Term Infrastructure Picture Looks Like
NCDOT and state officials have been debating permanent solutions for the Pea Island section for years. The options range from further road hardening and drainage improvements to more ambitious engineering. None of the long-term fixes are funded and shovel-ready as of the time I’m writing this. The conversation about how NCDOT weighs major coastal infrastructure decisions gives some context for how slow and politically complicated those processes tend to be — don’t assume a solution is coming on any particular timetable.
The Coastal Resources Commission has also been looking at N.C. 12 protections in the context of broader coastal rules, including septic setbacks and dune management. Those regulatory conversations affect what can be built near the road corridor, which in turn affects long-term land values on both sides.
What doesn’t get said enough: the state has a structural interest in keeping N.C. 12 open because Hatteras Island’s economy — and its tax base — depends on it. That’s not nothing. But “structural interest” doesn’t mean “guaranteed funding in the next legislative session.”
Before You Make an Offer on Hatteras Island Property
Run this checklist before you go to contract:
- Pull the NCDOT closure log for N.C. 12 at the relevant segment — how many closures in the last three years, how long each one lasted.
- Check Dare County’s FIMAN flood mapping for the specific parcel. Inundation risk at the property is separate from road closure risk, and you need to understand both.
- Get a current flood insurance quote — not an estimate, an actual quote tied to the address and your intended use.
- Ask for rental income records across a full calendar year, including any storm season adjustments or refunds issued.
- Confirm the elevation certificate is current (within the last two to three years). Elevation affects both your insurance premium and your resale position.
- Ask your inspector specifically about the foundation — posts, pilings, or slab — and what a week of standing water around the perimeter would do to it.
The road closing is not a reason to walk away from a Hatteras Island property automatically. People have been buying there for decades knowing the score. But the ones who make it work long-term are the ones who understood the access risk before they closed, not the ones who found out about it the hard way in January.